


A postponed listing clouds the financing picture, but the investment case for AI memory, storage and sovereign infrastructure extends well beyond the IPO calendar.
Wall Street has temporarily misplaced its enthusiasm for memory stocks. Artificial intelligence, inconveniently for the bears, still needs memory. SK hynix (NASDAQ: SKHY; KRX: 000660) has halted its review of a potential U.S. initial public offering for Solidigm, its flash-memory and solid-state-drive subsidiary. The proposed transaction could reportedly have valued Solidigm at up to $150 billion and raised $10 billion to $15 billion. That distinction matters: $150 billion was the potential valuation, not the amount the company expected to collect at the closing dinner. The immediate explanation is straightforward. Semiconductor shares have corrected, capital markets have become less accommodating, and management is reassessing whether a separate listing would serve existing shareholders. But SK hynix’s own statement draws an important line between financing conditions and operating prospects: Solidigm’s growth outlook and investment needs have not changed. That leaves many with a more interesting question than whether another technology company can ring an exchange bell. Is this a retreat in AI infrastructure demand, or a financing interruption inside a much larger expansion? The bullish case seems to rest on the latter: NVIDIA (NASDAQ: NVDA) is advancing increasingly integrated AI systems, memory bandwidth remains central to accelerator performance, and flash storage is taking on a more consequential role in AI inference. Meanwhile, sovereign AI initiatives are broadening the infrastructure opportunity beyond a relatively small club of global technology buyers.
The Solidigm IPO Pause Is Not an Order Cancellation
The canceled listing review deserves scrutiny, but it should not be confused with a canceled business plan. SK hynix says it will continue exploring alternative financing options for Solidigm’s expansion. Reuters reported that a potential listing had been considered to help fund a new U.S. factory and meet demand for chips used in AI data centers. The company is now reconsidering the timing, scale and financing of future investments rather than declaring that those investments are unnecessary. There is also a shareholder-governance dimension. Yonhap reported opposition from shareholders and regulatory scrutiny over whether a separate subsidiary listing could undermine minority shareholder interests. CNBC likewise reported concerns surrounding South Korea’s dual-listing rules. For many, the constructive interpretation is not that shelving an IPO automatically creates value. It is that management declined to treat a public offering as an obligation regardless of market conditions or ownership concerns. An IPO is a financing tool, not a corporate coming-of-age ceremony. Sometimes the grown-up decision is to leave the confetti in storage.The unresolved issue is consequential: Solidigm still needs capital. Alternative funding could carry costs, and investors should evaluate the eventual structure rather than assume that avoiding a listing makes expansion free.
A Sharp Stock Correction Does Not Settle the AI Demand Debate
The market backdrop explains why the financing window narrowed. Yahoo Finance reported that memory and storage stocks had lost approximately $1.3 trillion in market value from their 2026 peaks, with SK hynix and Micron Technology (NASDAQ: MU) accounting for substantial portions of that decline. The report also noted that 58 of 59 stocks in its semiconductor basket were down in October. Those figures describe the report’s selected universe and measurement period, not the entire global technology market. That is a serious repricing. It is not, by itself, proof that customers have stopped building AI infrastructure. Indeed, the same Yahoo Finance report describes memory manufacturers producing record profits while executives anticipate shortages extending into 2028. That contrast is the central investment tension: many are discounting the possibility of a cyclical peak while operating conditions still reflect substantial demand. Micron’s fiscal 2026 results provide another reference point. In its September earnings release, the company reported record fourth-quarter and full-year results and said AI-driven demand and operational execution positioned it for a record fiscal 2027. That is management’s outlook, not a guarantee, but it hardly reads like an industry packing up its equipment. The opportunity for many lies in distinguishing a lower share price from a lower-quality business outlook. The two can coincide. They need not.
NVIDIA Remains the Center of the AI Infrastructure Conversation
NVIDIA deserves particular attention because its platform direction helps explain why memory and storage remain strategically important. The company’s Vera Rubin architecture treats the data center as an integrated computing system rather than a collection of independently impressive chips. NVIDIA describes co-design spanning GPUs, CPUs, networking, power delivery, cooling and system architecture. Rubin also incorporates HBM4, the next generation of high-bandwidth memory. That architecture reinforces a basic point: an expensive accelerator is only as productive as the system that keeps it supplied with data. NVIDIA’s technical description of Rubin specifies memory bandwidth of up to 22 terabytes per second, a 2.8-fold increase over Blackwell and Blackwell Ultra. Those are company-published specifications, but their strategic significance is clear. Memory bandwidth is receiving substantial engineering attention because moving data is fundamental to useful AI performance. For SK hynix and other qualified memory suppliers, the investment thesis is therefore tied to more than the number of accelerators sold. It also depends on the memory requirements of successive platforms, supplier qualification, manufacturing execution and the economics of serving those systems. For NVIDIA shareholders, the appeal is broader. The company is positioning its architecture across the infrastructure stack, making the performance of memory, storage and networking increasingly relevant to the value of the overall platform. The GPU may remain the celebrity. The supporting cast is negotiating a better contract.
HBM and Flash Storage Play Different Roles, and Both Matter
A useful AI investment story must keep its memory categories straight. High-bandwidth memory sits close to the accelerator and supports rapid data access. Solidigm’s NAND flash-based SSDs serve a different role, providing storage capacity within the wider infrastructure architecture. They are not interchangeable products, even when both benefit from AI investment. What is changing is how storage participates in AI workloads. As inference systems handle longer conversations and repeated reasoning tasks, they must manage larger amounts of contextual information. Solidigm describes NVIDIA’s Inference Context Memory Storage Platform as introducing a flash-backed context layer that can retain and share information used during inference. Its purpose is to bridge part of the gap between fast GPU memory and scalable shared storage. In practical terms, the system can preserve useful context instead of repeatedly reconstructing it. That makes storage relevant not just to where information resides, but also to how efficiently AI systems work. Solidigm’s published testing with Metrum AI offers a concrete example. In one vector-search configuration involving 100 million vectors, the company reported reducing DRAM requirements from 331 gigabytes to 116 gigabytes by using SSD-backed indexing. These are vendor-reported results from a particular configuration, not a universal performance promise. Still, they illustrate the economic logic behind moving selected workloads onto a more cost-efficient storage tier. Solidigm’s technical material also describes work involving NVIDIA BlueField data processing units to manage storage for inference context. That gives the broader thesis substance: the relationship between AI compute and storage is an architectural issue, not merely an enthusiastic addition to an earnings presentation.
Sovereign AI Could Broaden the Customer Base
The next layer of the opportunity is geographic as well as technological. NVIDIA describes sovereign AI as countries building domestic infrastructure, models and expertise so that AI systems can reflect local languages, institutions and requirements. Its public-sector materials emphasize sensitive-data protection, domestic capabilities and long-term AI readiness. That creates a different purchasing rationale from a conventional corporate technology upgrade. A government may want domestic AI capacity to support research, public services, national-language models or control over sensitive information. Those objectives can require infrastructure that is locally governed rather than simply accessible through an overseas service. NVIDIA’s account of national AI deployments describes countries investing in infrastructure, local datasets and domestic expertise to address those priorities. For the supply chain, the potential implication is a broader pool of customers for compute, memory, storage, networking and deployment services. The qualification is important: sovereign ambitions do not automatically become funded projects. Financing, procurement, energy availability and execution determine whether an attractive national strategy becomes operating infrastructure. Nevertheless, this is a meaningful expansion of the AI discussion. The prospective buyer is no longer always a technology company. Sometimes it is a country.
Seven Boson Group Brings the Sovereign Deployment Layer Into Focus
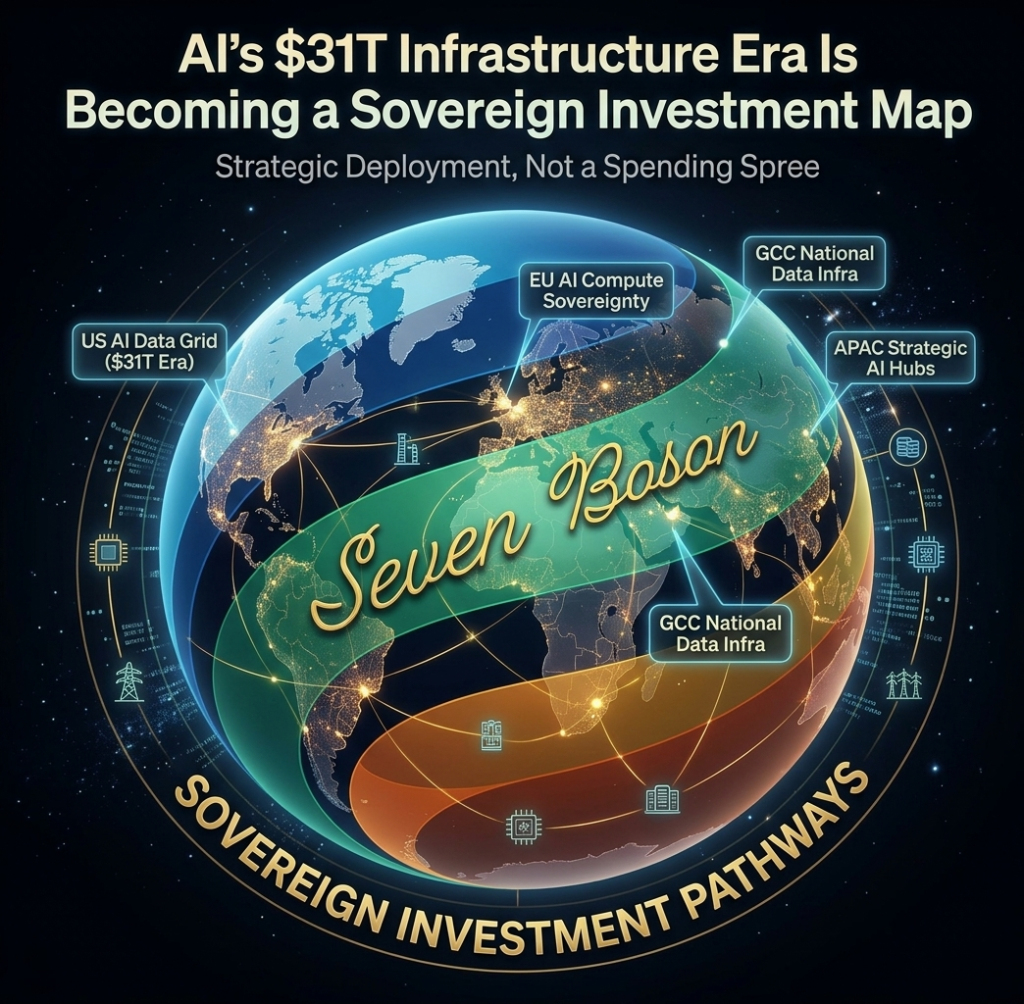
That is where Seven Boson Group enters the story. Seven Boson Group describes its offering as sovereign-controlled AI decision intelligence deployed in-country and governed locally for government and enterprise customers. Its stated scope includes sovereign AI cloud infrastructure, governance and oversight, secure research environments, and renewable generation and storage intended to support high-availability computing. The company’s positioning addresses a practical issue that hardware-focused investment narratives can overlook: purchasing compute does not, by itself, establish a locally governed AI capability. Seven Boson says its delivery models include government- and enterprise-owned structures, public-private partnerships and concessions. It also outlines a process spanning national blueprint development, integration, operation and transfer. That makes Seven Boson relevant to the broader infrastructure thesis as a proposed deployment and governance layer, rather than as another memory manufacturer or accelerator designer. The distinction matters. NVIDIA’s platform materials address the technology foundation for national AI capabilities. Seven Boson’s website emphasizes how sovereign systems would be deployed, governed and supported with energy infrastructure. Those are related parts of the same infrastructure conversation, but the reviewed materials do not establish a commercial relationship between the two companies. Seven Boson’s relevance here is therefore its stated strategic positioning. For many tracking the sector, the useful insight is the category itself: sovereign AI needs more than chips. It also needs institutions, local operating authority and an implementation model.
What Many Should Watch Next
The constructive case becomes more credible when it is tied to measurable developments rather than the assumption that every correction is a gift. Four issues deserve attention:
- Solidigm’s financing structure. SK hynix has preserved its expansion ambitions, but the cost and ownership implications of alternative funding remain important.
- Memory suppliers’ execution. HBM demand creates an opportunity, but competitive positioning still depends on manufacturing capability, customer qualification and delivery. Industry reporting shows a concentrated market with active competition among leading suppliers.
- Adoption of inference-oriented storage. Solidigm’s work on context storage and SSD offloading provides technical evidence for the opportunity. Investors still need to distinguish promising architectures from material commercial contribution.
- Conversion of sovereign AI plans into deployments. Domestic AI strategies can expand the customer base, but operating systems and funded projects matter more than announcements. NVIDIA’s national AI materials explain the scope of the opportunity without eliminating execution risk.
The Bigger Story Is Still Being Built
SK hynix’s decision to halt Solidigm’s IPO review is a setback for one financing route. The company’s statement does not describe a retreat from Solidigm’s growth prospects or investment needs. At the same time, NVIDIA’s platform development continues to emphasize faster memory, integrated infrastructure and new approaches to inference context. Solidigm’s technical work shows why flash storage can participate in that evolution, while sovereign AI initiatives introduce additional reasons for countries to build domestic computing capacity. That is the strongest constructive reading of the moment: the market has repriced the securities more quickly than the industry has abandoned its infrastructure ambitions. For SK hynix, NVIDIA and the wider AI supply chain, the investment question is not whether the IPO window reopens on schedule. It is whether the infrastructure being financed earns attractive returns once it is built. Wall Street can postpone a debut. It cannot make a useful AI system run on applause.
The Sources
- Yahoo Finance: “SK Hynix pulls a $150 billion IPO as its own record US listing sits underwater”
- SK hynix: “Solidigm to Discontinue Review of Potential IPO”
- Reuters, via KSL: “SK Hynix says Solidigm suspends review of US IPO, citing market conditions”
- Yonhap News Agency: “SK hynix halts review of Solidigm U.S. IPO”
- CNBC: SK hynix shares and the suspension of Solidigm’s IPO plans
- Micron Technology: “Reports Record Fiscal Fourth Quarter and Full Year 2026 Results”
- NVIDIA: “Inside the NVIDIA Vera Rubin Platform: Six New Chips, One AI Supercomputer”
- NVIDIA: “Inside NVIDIA Rubin GPU Architecture: Powering the Era of Agentic AI”
- Solidigm: NVIDIA Inference Context Memory Storage Platform and flash storage
- Solidigm: “KV Cache Data Offload to SSDs as an Active Performance Tier”
- Solidigm: “AI Inference Storage Powered by CSAL on BlueField-3 DPUs”
- NVIDIA: “National Transformation With AI”
- NVIDIA: “How Nations Are Deploying AI for Strategic Priorities”
- The Chosun Daily: “South Korea Dominates HBM for AI Chips”
- Seven Boson Group: Sovereign-Controlled AI Decision Intelligence
Stay Updated with Vista Partners
Subscribe to receive market insights, investing ideas, and the latest updates directly in your inbox.
The Doctor Will Zoom You Now: Doximity’s Telehealth Moat And AI Suite Power A Surprise Aftermarket Recovery -( $DOCS )