A New Bank for Companies Building the Future
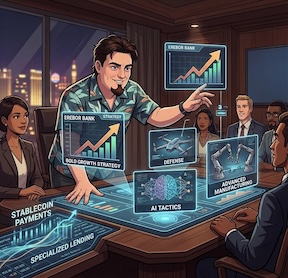
America’s next industrial expansion will need more than powerful chips, ambitious founders and factories with unusually expensive electrical bills. It will need banks that understand what those businesses are building. Erebor Bank is making a compelling early case that specialized banking belongs near the center of that expansion. The Columbus, Ohio-based national bank said on October 15 that it had surpassed $8 billion in assets after opening earlier in 2026. Its customers operate across manufacturing, aerospace, defense, robotics, artificial intelligence and energy, giving the young institution exposure to several industries reshaping the American economy. For many watching the convergence of technology and finance, the attraction is straightforward: Erebor aims to become financial infrastructure for businesses whose ambitions do not fit neatly into conventional lending categories. The opportunity is not simply to build another banking app. America is reasonably well supplied with those. It is to combine technical underwriting, a regulated balance sheet and modern payments infrastructure into a bank designed around the needs of capital-intensive technology companies.
A National Charter Changes the Equation
Erebor’s most important asset may not be its software. It is the legal authority underneath it. The Office of the Comptroller of the Currency received Erebor’s charter application in June 2025, granted preliminary conditional approval on October 15 and recorded the charter as effective on February 6, 2026. The process took less than eight months from receipt to effectiveness. That distinction separates Erebor from financial technology platforms that rely on another institution to provide the underlying banking services. Erebor’s application proposed an insured national bank, putting deposits, lending and regulatory responsibility inside the institution itself. Its subsequent community reinvestment plan identifies it as a chartered national bank granted deposit insurance on February 6. Owning the bank gives management greater control over product development and customer relationships. It also means owning the obligations that come with banking. A charter is a competitive asset, not a permission slip to ignore credit risk. The OCC’s approval announcement explicitly said Erebor underwent the same rigorous review and standards applied to other charter applications. That matters when assessing a company whose rapid approval has attracted almost as much attention as its business model.
The Leadership Story Is More Than a Famous Founder
Palmer Luckey, an American entrepreneur and co-founder of defense technology company Anduril Industries & the founder of Oculus VR and designer of the Oculus Rift, a virtual reality headset that is widely credited with reviving the virtual reality industry, supplies the entrepreneurial profile and strategic vision, but Erebor’s operating structure deserves a more precise description than “a billionaire’s bank.” The bank’s October announcement identifies Owen Rapaport as co-founder and CEO. An August account from payments company Airwallex identifies Jacob Hirshman as chief strategy officer and Michael Hagedorn as president, with Luckey providing board-level oversight rather than running daily operations. That combination is central to the thesis. Technical familiarity can help a lender recognize an opportunity. Banking experience determines whether recognizing it produces an attractive loan or an expensive learning experience. Erebor is attempting to bring both capabilities into the same room.
Why AI Hardware and Defense Finance Create an Opening
Erebor’s proposed advantage is specialized judgment. Airwallex’s account describes a strategy involving financing for advanced AI hardware and credit secured by unconventional assets, including cryptocurrency and private securities. The video above similarly presents a bank seeking to evaluate technology equipment and complex business relationships that may fall outside a generalist lender’s preferred framework. Consider equipment built around NVIDIA (NASDAQ: NVDA) processors. The bullish argument is not that every chip deserves a loan. It is that a lender capable of evaluating equipment, customer contracts and repayment capacity may identify viable credit opportunities that a less specialized institution declines. The broader financing market is already developing sophisticated approaches to digital infrastructure. In November, the Commercial Real Estate Finance Council highlighted power availability, tenant concentration, technology requirements and refinancing risk as important underwriting considerations for data centers. Expertise, in other words, is becoming part of the financial product. That is Erebor’s opening: not reckless willingness to finance anything futuristic, but the possibility of pricing complicated assets more intelligently. The best outcome would turn technical understanding into repeat business across deposits, payments, treasury services and credit.
Rapid Deposit Growth Offers an Early Demand Signal
The video above reports that Erebor accumulated approximately $1.1 billion in deposits during its first seven weeks, reached roughly $4.1 billion by the end of June and approached $4.6 billion by July. It also cites third-party estimates placing annualized revenue at $112 million in July, compared with $31 million in March. These are historical figures and estimates presented in the video, not audited full-year results. The later company announcement provides a more recent milestone: more than $8 billion in assets by mid-October. Assets and deposits are different measures, so those figures should not be presented as interchangeable evidence of deposit growth. Nevertheless, the October statement establishes that the institution’s reported scale had advanced considerably beyond its opening months. The commercial implication is encouraging. Specialized companies appear willing to consider a new banking relationship when the institution speaks their operational language. The next test is more demanding: turning that early scale into durable earnings. A large balance sheet can open the conversation. Attractive funding costs, disciplined credit and recurring fees determine whether the conversation becomes a franchise.
Stablecoins Add Utility, Not Just a Fashionable Vocabulary
Erebor’s digital-asset strategy is most interesting when viewed as a treasury tool rather than a cryptocurrency slogan. Its model includes blockchain-enabled settlement and banking infrastructure for financial technology partners. The potential benefit is practical: businesses operating across jurisdictions and outside conventional banking hours may value another way to move funds and manage liquidity. There is public-company evidence that stablecoin activity has reached meaningful scale. Circle Internet Group (NYSE: CRCL), issuer of USDC, reported $13.9 trillion in USDC onchain transaction volume for the third quarter of 2026, up 49% year over year. Transaction volume is not revenue or a measure of unique commercial payments, but it illustrates the scale of activity on these networks. Circle’s SEC filings also demonstrate the importance of interest-rate exposure. Its second-quarter filing showed reserve income representing 95.2% of total revenue, underscoring how strongly digital-dollar economics can depend on returns earned on backing assets. For Erebor, the more attractive long-term possibility is a combination of spread income and payment-related service revenue. Multiple revenue sources would give the business more ways to grow than simply waiting for the next interest payment. Still, stablecoins and insured bank deposits are not the same product. Airwallex’s description explicitly distinguishes potentially insured fiat balances from uninsured stablecoin holdings.
The Giants Validate the Market
Erebor is not alone in pursuing always-on finance. JPMorgan Chase (NYSE: JPM) is expanding blockchain-based deposit infrastructure through Kinexys. A January announcement outlined plans to bring its JPM Coin deposit token to the Canton Network, with near-instant transfers and redemptions contemplated as part of a phased integration. That initiative also challenges the idea that large banks’ digital payment capabilities must remain permanently confined to their own internal systems. For Erebor, this is both competition and validation. The market is important enough to attract one of the world’s largest banks. The opportunity for a specialist is to pair comparable convenience with closer understanding of a particular customer’s business. A defense company may appreciate a global balance sheet. It may also appreciate not having to begin every credit discussion with a seminar.
Capital Discipline Will Decide Whether the Story Compounds
Erebor’s regulatory conditions provide an important anchor for the bullish case. The OCC required a minimum 12% leverage ratio during the bank’s first three years. The approval documents also describe its intended use of the community bank leverage ratio framework, under which a 9% Tier 1 leverage ratio is the relevant well-capitalized benchmark. That is a more appropriate comparison than casually contrasting Erebor’s requirement with a generic 5% threshold. The cushion matters because rapid growth creates capital demands. Deposits provide funding, but they do not substitute for shareholder capital. Political scrutiny also remains part of the landscape. Senator Elizabeth Warren’s February letter questioned Erebor’s approval process and the potential influence of its founders’ political connections. Those questions warrant attention, but allegations should not be confused with regulatory findings of wrongdoing. The central operating challenge is equally clear: a specialized customer base can create valuable relationships while also concentrating exposure to related industries and funding cycles. The bullish thesis therefore depends on disciplined execution, not merely a well-connected address book.
An Industrial Bank With a Wider Community Strategy
Erebor’s October announcement added a useful dimension to its technology-focused identity. The bank committed $20 million to financial institutions in Columbus, beginning with Adelphi Bank, and appointed former Housing and Urban Development Secretary Marcia Fudge to chair its nationwide Opportunity Initiative. The stated aim is to support community-based commercial opportunities, including housing, workforce training and healthcare, in places where its customers operate. That strategy connects frontier technology to the local economies supporting it. Factories require workers. Workers require housing and services. Industrial development becomes more durable when the surrounding community has access to capital as well. Erebor’s community reinvestment plan, published through the OCC, provides an additional formal context for those responsibilities.
The Bullish Case: Banking Can Be Part of the Technology Stack
Erebor’s appeal rests on a focused proposition: companies building sophisticated physical and digital infrastructure may benefit from a bank that understands both. The early evidence supports taking that proposition seriously. Erebor obtained its national charter, built substantial reported scale and articulated a business spanning specialized lending, deposits and modern settlement. Its October announcement shows an institution already looking beyond its original technology constituency toward a broader role in industrial communities. That does not make every reported private valuation attractive, nor does it establish a timetable for a public offering. Nothing in the public domain that we could locate currently identifies an announced IPO timeline. What sources do seem to establish is a business worth watching for many following American reindustrialization. The next generation of important companies will need financing as surely as it needs electricity. Erebor’s wager is that the bank capable of understanding the machinery can earn a lasting place beside it. In an economy increasingly powered by advanced computing, there may still be excellent money in understanding the customer.
The Sources
- Aaron Ross: “Palmer Luckey’s Plan to Reinvent American Banking (Erebor)”
- Erebor Bank: October 15, 2026 Opportunity Initiative announcement
- OCC: Erebor charter application status and effective date
- OCC: Erebor Bank national charter application
- OCC: Conditional approval announcement, October 15, 2025
- OCC: Conditional Approval No. 1348 and capital requirements
- OCC: Erebor Bank community reinvestment plan
- Airwallex: Erebor Bank strategy, leadership and services
- SEC.gov: Circle Internet Group, second-quarter 2026 Form 10-Q
- SEC.gov: Circle Internet Group, third-quarter 2026 results
- Digital Asset and Kinexys: Planned JPM Coin integration with Canton
- Senate Banking Committee: Senator Warren’s February 2026 letter to Palmer Luckey
- Commercial Real Estate Finance Council: Updated data center financing primer
Stay Updated with Vista Partners
Subscribe to receive market insights, investing ideas, and the latest updates directly in your inbox.