Wall Street Price targets of $16, $17 and $18 seem to underscore the potential for a long-acting treatment as December clinical data approach
Eupraxia Pharmaceuticals (NASDAQ: EPRX; TSX: EPRX) has received a timely vote of confidence from three research firms, with newly published reports arguing that encouraging results from a large pharmaceutical competitor have not closed the door on its experimental treatment for eosinophilic esophagitis, or EoE. Oppenheimer and LifeSci Capital maintained Outperform ratings, while Raymond James reiterated Strong Buy. Their research supports a bullish investment case centered on durability, treatment convenience and an approaching clinical catalyst. The reports, dated October 11 and October 12, examine the competitive implications of Phase 3 results for Tezspire, developed by Amgen (NASDAQ: AMGN) and AstraZeneca (NYSE: AZN). Their shared conclusion is not that biologics have disappointed patients. It is that effective biologics still leave room for a different treatment model, particularly one that could deliver sustained relief after a single endoscopic administration. For Eupraxia, that proposition rests on EP-104GI, its investigational, locally delivered, extended-release formulation of fluticasone propionate. Randomized Phase 2b interim results are expected in December 2026. If those results reinforce the earlier durability signals, many could have more than an interesting delivery technology to discuss. They could have a clearer view of a commercially differentiated drug candidate. In biotechnology, convenience rarely gets the opening keynote. It can, however, become rather important when treatment turns into a standing appointment with the medicine cabinet.
Three Reports, Three Bullish Perspectives on EPRX
The new research approaches Eupraxia’s opportunity from complementary angles: long-duration treatment, room for multiple commercial winners and a potential position before biologics in the treatment sequence.
Oppenheimer: A $17 Target Built Around Long-Lasting Disease Control
Oppenheimer’s October 11 report maintains an Outperform rating and a $17 price target over 12 to 18 months. Against the $7.46 reference price shown in the report, that target implies approximately 128% upside. This is an analyst valuation scenario, not a forecast of a guaranteed return. The firm’s central argument is that Tezspire’s strong histologic results do not eliminate the opportunity for an alternative that requires substantially fewer treatment occasions. Tezspire was studied with injections every four weeks. EP-104GI is being developed with the potential for once-yearly administration, contingent on further clinical validation and regulatory approval. Oppenheimer emphasizes that randomized evidence must confirm durability, tissue-health improvements and safety. Its $17 valuation uses a discounted cash flow model with a 12% discount rate and forecasts approximately $1.2 billion in risk-adjusted peak total revenue in 2040. That figure is a long-range modeling assumption, not current revenue or an established market outcome. The bullish interpretation is straightforward: Eupraxia may not need to displace every biologic prescription to create substantial value. It needs to establish a sufficiently compelling clinical and practical reason for physicians to choose a different approach.
LifeSci Capital: A $16 Target and Room for More Than One Winner
LifeSci Capital’s October 11 update maintains Outperform and a $16 twelve-month price target, implying approximately 114% upside from the same $7.46 reference price. Its analysts argue that the addressable populations for EP-104GI and biologics overlap without being identical. They see EP-104GI competing largely within the steroid-treatment population, while potentially offering an option for some patients who have not responded adequately to biologics. They also believe an in-clinic, potentially annual treatment could appeal to patients and providers who prefer it to repeated at-home injections. LifeSci’s model assumes a global launch in 2030 and approximately $1.52 billion in peak worldwide sales in 2044 before risk adjustment, or $912 million after risk adjustment. The model assigns EP-104GI a 60% probability of success at its current development stage. Its assumed $50,000 annual U.S. net price is a valuation input, not company-announced pricing. That distinction matters. A research model can illuminate the potential economics of a successful product, but it cannot turn an investigational therapy into an approved one.
Raymond James: Strong Buy, With an $18 Target in Its Published Target History
Raymond James’ October 12 report reiterates Strong Buy. Its target-history section shows the latest listed target at $18, established February 19, 2026. Relative to the October 9 reference price of $7.46, that represents approximately 141% potential upside. The October update does not announce a new target increase. The firm focuses on swallowing symptoms and treatment positioning. Although Tezspire delivered competitive histologic remission results, its placebo-adjusted improvement in dysphagia appeared smaller than that reported in Dupixent’s pivotal studies. Raymond James believes steroid therapies are likely to remain an important second-line option after inadequate response to proton pump inhibitors, with biologics often used later. It views EP-104GI as potentially well positioned within that sequence, subject to the forthcoming RESOLVE results. Its valuation uses a risk-adjusted, sum-of-the-parts discounted cash flow analysis, weighting a base scenario at 75% and an acquisition scenario at 25%. That acquisition component is a modeling assumption, not evidence of an active transaction. Taken together, the three reports offer a concentrated expression of analyst optimism. They are not a comprehensive survey of Wall Street coverage, and their targets depend on clinical and commercial assumptions that remain unproven.
What the Tezspire Results Mean for Eupraxia
Tezspire’s Phase 3 CROSSING trial succeeded on both co-primary endpoints: histologic remission and improvement in difficulty swallowing. AstraZeneca reported that benefits were maintained through week 52 with continued every-four-week treatment, with a safety profile generally consistent with its approved indications. These are meaningful competitive results, not a failed rival program. The detailed figures summarized in the analyst reports nevertheless explain why the firms remain constructive on Eupraxia:
- Histologic remission at week 24 reached 64.8% with Tezspire 210 mg and 68.9% with 420 mg, compared with 3.5% for placebo.
- Placebo-adjusted improvement on the Dysphagia Symptom Questionnaire, or DSQ, was approximately 4.1 points at the lower dose and 7.3 points at the higher dose. Lower scores indicate less severe symptoms.
- In the cited pivotal Dupixent studies, placebo-adjusted DSQ improvement was approximately 9.9 to 12.3 points.
Dupixent, developed by Regeneron Pharmaceuticals (NASDAQ: REGN) and Sanofi (NASDAQ: SNY), remains the established biologic benchmark discussed in the reports. For EoE patients weighing at least 40 kilograms, its labeled regimen is 300 mg weekly. Lower-weight pediatric patients receive different regimens. These comparisons are informative, but they are not head-to-head evidence. Differences in patient populations, prior treatments and placebo responses can influence results. The data do not establish that EP-104GI is superior to either biologic. Instead, the research points to a more nuanced opportunity: strong control of inflammation is valuable, but patients also need to swallow more comfortably and sustain that improvement with a treatment regimen they can manage. A favorable biopsy is important. A less anxious dinner is important, too.
EP-104GI’s Differentiation: Local Delivery, Potentially Annual Treatment
EP-104GI uses Eupraxia’s Diffusphere technology to deliver fluticasone propionate locally into the esophageal wall. The formulation is designed to release the drug over an extended period, with the aim of sustaining treatment effects while limiting systemic exposure. Administration involves multiple injection sites during an endoscopic procedure, rather than a single at-home injection. The most recent company update provides an encouraging, but early, durability signal. On September 30, Eupraxia reported that nine of 14 evaluable patients across the longer-followed Phase 1b/2a cohorts, or 64%, remained in clinical remission at 52 weeks after one administration. In the highest-dose cohort, two of three patients met the clinical-remission definition at that time point. The populations are small, and the Phase 1b/2a study is open-label. Clinical remission in this portion of RESOLVE is defined using the Straumann Dysphagia Index, or SDI, rather than the histologic-remission measure reported for Tezspire. The percentages therefore should not be treated as interchangeable measures of efficacy. Eupraxia also reported no treatment-emergent or procedure-related serious adverse events and no observed cases of oropharyngeal candidiasis, adrenal insufficiency or glucose derangement in the reported experience. Those observations support further development, but the small early-stage dataset cannot establish the frequency of uncommon risks or prove a safety advantage over competing therapies. The opportunity lies in whether a larger randomized study can preserve the signal: meaningful swallowing improvement, healthier tissue and a long interval before another treatment is required.
The EoE Market: A Large Patient Population With Unfinished Business
EoE is a chronic inflammatory disease of the esophagus that can cause difficulty swallowing, food impaction and narrowing of the esophagus. AstraZeneca estimates that it affects more than 470,000 people in the United States and reports that nearly half of patients do not achieve adequate disease control with existing first-line approaches. That creates an opportunity broader than a simple contest between competing biologics. LifeSci highlights an estimated 6% to 8% biologic penetration for Dupixent, citing a June estimate from Apogee Therapeutics (NASDAQ: APGE). That estimate should not be interpreted to mean that all remaining patients are untreated or eligible for EP-104GI. It does support the analysts’ view that the EoE market could expand as additional treatment options become available. Market estimates also require care. LifeSci’s valuation model uses a narrower assumption of approximately 375,000 diagnosed U.S. patients, citing Takeda Pharmaceutical (NYSE: TAK), with about 190,000 receiving treatment. Those figures serve a different modeling purpose from the broader prevalence estimate of more than 470,000 people. They should not be blended into a single patient count. For Eupraxia, the potential commercial opening has three dimensions:
- Treatment frequency: A validated annual regimen could reduce the burden of repeated dosing.
- Treatment positioning: Analysts see an opportunity among patients who need additional therapy after proton pump inhibitors, including those considering steroid treatment before biologics.
- Clinic integration: LifeSci believes administration alongside routine endoscopic care could fit gastroenterology practice workflows, although commercial adoption would still depend on procedure acceptance, reimbursement and clinical performance.
This is why the bullish thesis need not require a winner-take-all market. Multiple therapies could succeed by serving different patients, treatment stages and preferences.
December’s RESOLVE Results Are the Next Major Test
Eupraxia expects interim Phase 2b RESOLVE results in December 2026. The randomized, placebo-controlled portion is evaluating two dose levels of EP-104GI, moving the program beyond the small open-label cohorts that underpin much of today’s enthusiasm. LifeSci describes an anticipated update from the 120-patient study that could include approximately 90 patients with three-month follow-up, more than 60 with six-month follow-up, more than 40 with nine-month follow-up and more than 20 with one-year follow-up. These are expectations presented in the research report, not guaranteed final data counts. Many will be watching whether swallowing symptoms improve relative to placebo, whether tissue and endoscopic findings support the symptom results, and whether the duration and safety profile justify continued development. Oppenheimer identifies an FDA end-of-Phase-2 meeting in the first half of 2027 and potential Phase 3 initiation around mid-2027 as subsequent anticipated milestones.The strongest possible read-through would not simply be another attractive remission percentage. It would be a coherent randomized dataset showing that the delivery approach produces a benefit patients notice and that lasts long enough to matter commercially.
A Bullish Opportunity, With Clinical Risk Still Attached
The three new reports strengthen the case for watching Eupraxia closely. They suggest that Tezspire’s success validates the importance of the EoE market without exhausting its commercial possibilities, and that EP-104GI’s potential differentiation remains intact ahead of December’s results. But EPRX remains a clinical-stage biotechnology investment. EP-104GI is investigational, annual dosing has not been established as an approved regimen, and development still carries efficacy, safety, regulatory, manufacturing, financing and reimbursement risks. Additional capital could dilute existing shareholders, however Eupraxia recently confirmed that they anticipate that existing cash reserves will be sufficient to fund the Company into the second half of 2028. The bullish case is therefore conditional, but substantial: if randomized RESOLVE data confirm durable symptom relief and supportive tissue-health findings, Eupraxia could move closer to offering a distinct treatment option in a large, incompletely served market. The $16, $17 and $18 analyst targets show how three firms value that possibility today. December’s data will help determine how much of the possibility deserves to become conviction. Note that the EP-104GI program is currently not partnered and therefore provides an interesting opportunity for any Pharmaceutical company seeking to ‘punch a non-dilutive ticket’ into the EOE market.
Join The Tribe in Nashville
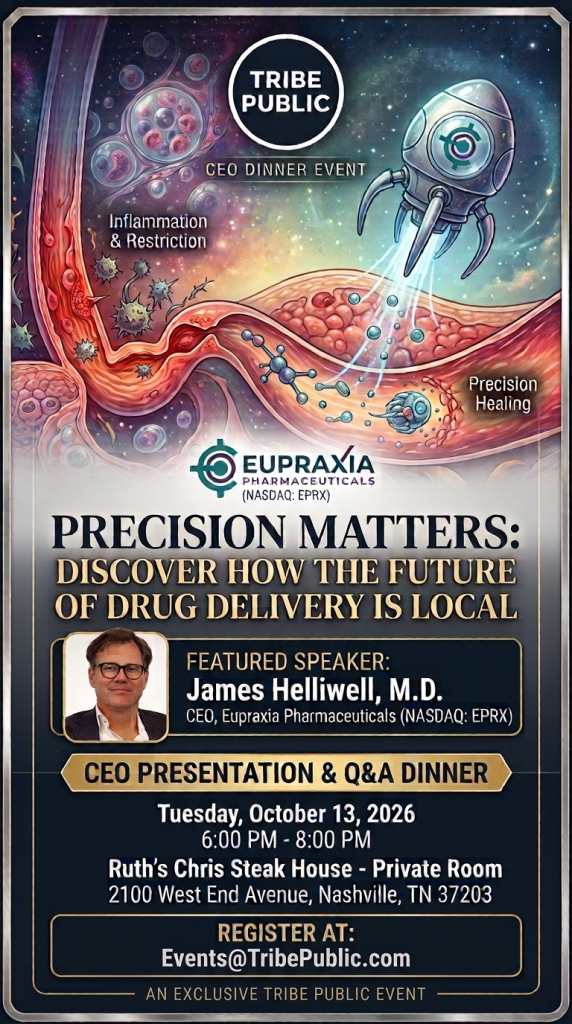
If you have not attended one of Tribe Public’s dinners or luncheon events across its 41 U.S. event venues, the format is designed to offer RSVP-only, corporate-sponsored access to management teams and industry experts across a broad range of sectors and investment interests. The gatherings bring together family offices, portfolio managers, accredited investors, business owners, media professionals, and community members interested in hearing directly from corporate leaders while sharing a complimentary, time-efficient private meal. More information is available at Tribe Public. Tribe Public’s next Nashville corporate-sponsored CEO presentation and Q&A dinner, “Precision Matters: Discover How The Future Of Drug Delivery Is Local,” is scheduled for Tuesday, October 13, from 6:00–8:00 PM at the private room at Ruth’s Chris Steak House, 2100 West End Avenue, Nashville, Tennessee 37203.
Space is limited. To reserve a seat, or request seating for friends, family members, or colleagues, email Events@TribePublic.com.
The Sources
[1] EPRX-Raymond James report must be accessed directly from Raymond James.
[2] EPRX-Oppenheiner analyst report must be accessed directly from Oppenheimer.
[3] EPRX-LifeSci analyst report must be accessed directly from LifeSci.
[4] Eupraxia Pharmaceuticals Reports 52-Week Data from the https://finance.yahoo.com/healthcare/articles/eupraxia-pharmaceuticals-reports-52-week-120000819.html
[5] Tezspire demonstrates positive Phase III results in eosinophilic https://www.astrazeneca.com/media-centre/press-releases/2026/tezspire-crossing-trial-met-primary-endpoints.html
[6] EoE Dosage & Administration | DUPIXENT® (dupilumab) https://www.dupixenthcp.com/eoe/dosage-administration
[7] Press Release: FDA approves Dupixent® (dupilumab) as first https://www.sanofi.com/en/media-room/press-releases/2022/2022-05-20-19-15-00-2447906
[8] [PDF] DUPIXENT® Full Prescribing Information | Regeneron https://www.regeneron.com/downloads/dupixent_fpi.pdf
[9] Eupraxia Pharmaceuticals Inc (EPRX-T) Stock Price and https://www.theglobeandmail.com/investing/markets/stocks/EPRX-T/
[10] Dupixent® (dupilumab) Demonstrates Improved Esophageal https://newsroom.regeneron.com/news-releases/news-release-details/dupixentr-dupilumab-demonstrates-improved-esophageal-function
[11] Eupraxia Pharmaceuticals Reports 52-Week Data from the Highest https://www.nasdaq.com/press-release/eupraxia-pharmaceuticals-reports-52-week-data-highest-dose-cohort-ep-104gi-its
[12] How DUPIXENT® (dupilumab) is Taken: EoE Dosing https://www.dupixent.com/eoe/taking-dupixent/dosing
[13] Eupraxia Pharmaceuticals to Present at Upcoming https://www.nasdaq.com/press-release/eupraxia-pharmaceuticals-present-upcoming-american-college-gastroenterology-acg-and
[14] Eupraxia Pharmaceuticals Reports Positive Tissue Health Data from https://www.nasdaq.com/press-release/eupraxia-pharmaceuticals-reports-positive-tissue-health-data-its-ongoing-resolve
[15] Eupraxia Pharmaceuticals Reports EREFS Data from its https://www.nasdaq.com/press-release/eupraxia-pharmaceuticals-reports-erefs-data-its-ongoing-phase-1b-2a-resolve-trial
[16] TEZSPIRE demonstrates positive Phase III results in eosinophilic https://www.astrazeneca.com/content/az-us/media/press-releases/2026/TEZSPIRE-CROSSING-TRIAL-MET-PRIMARY-ENDPOINTS.html
[17] Eupraxia reports 52-week data from EoE treatment trial – Investing.com https://www.investing.com/news/company-news/eupraxia-reports-52week-data-from-eoe-treatment-trial-93CH-4925006
[18] Dupixent claims new territory in eosinophilic oesophagitis https://pharmaphorum.com/news/dupixent-claims-new-territory-in-eosinophilic-oesophagitis
Stay Updated with Vista Partners
Subscribe to receive market insights, investing ideas, and the latest updates directly in your inbox.