


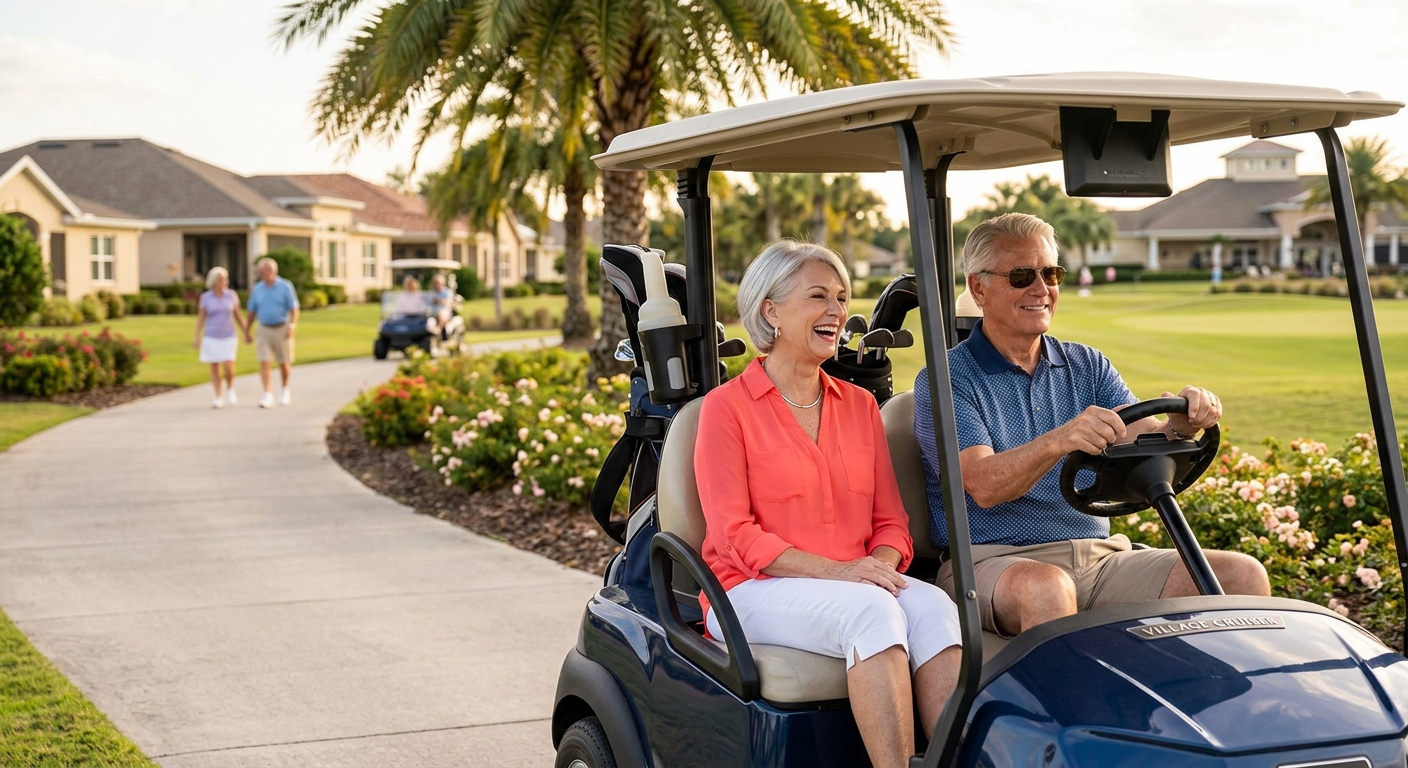
A $180 million expansion in Florida, a richer income opportunity for savers and an airline chief’s inheritance-tax proposal reveal where the next chapter of American wealth could unfold.
America’s retirement economy is offering investors an intriguing combination: more potential customers, substantial demand for lifestyle-oriented housing and government bonds that are once again competing seriously for savers’ attention. The opportunity is not simply to invest in an aging population. It is to understand how that population intends to live, spend and preserve its wealth. Consider three developments. The Villages, the sprawling Florida retirement community, is preparing an almost $180 million debt offering to support another round of residential development. Yahoo Finance reports that the 10-year Treasury yield closed at 5.09% on Friday. Meanwhile, Scott Kirby, chief executive of United Airlines Holdings (NASDAQ: UAL), has endorsed inheritance taxes approaching 100% above some unspecified wealth threshold .Together, these stories illuminate a potentially powerful investment theme: the growing commercial value of retirement, alongside an increasingly consequential debate over who gets to accumulate wealth and pass it on. The golf carts may move slowly. The capital does not.
The Villages’ $180 Million Expansion Makes a Bullish Statement
The Villages is seeking to issue almost $180 million in unrated, high-yield debt to finance development that includes 3,860 residential units, recreation centers and 27 holes of championship golf, according to Bloomberg’s report carried by Yahoo Finance. The offering is expected to price October 20. This is not a small subdivision with an ambitious clubhouse. The 57,000-acre community has about 170,000 residents. Its longer-term plans call for a population exceeding 260,000 and more than 130,000 homes over the next two decades. Bloomberg reports that about 83,400 residential units have already been sold to its age-restricted population. The near-term sales figures also deserve attention. More than 2,100 homes have sold this year, with the average sales price just below $500,000. Those figures suggest that a meaningful pool of buyers remains willing to commit substantial capital to a retirement lifestyle built around convenience, recreation and community. The bullish interpretation is straightforward: retirement housing can be more than a transaction involving square footage. It can be a bundled consumer offering, combining a home with amenities and social infrastructure. In that business model, the clubhouse is not merely somewhere to misplace a cardigan. It is part of the product. Still, the financing label matters. An unrated, high-yield development bond is not a Treasury substitute. The expansion demonstrates ambition and access to financing, not a guarantee of repayment or investment performance. Investors would need the offering documents to assess security, repayment sources, development assumptions and other risks.
The Demographic Tailwind Is Already Here
The case for retirement-oriented businesses does not require a heroic forecast. The U.S. Census Bureau reported that the population age 65 and older increased 3.1% to 61.2 million between 2023 and 2024. During the same period, the population under 18 declined 0.2% to 73.1 million. Older adults outnumbered children in 11 states and nearly 45% of U.S. counties in 2024.Those figures do not establish that every retirement development will succeed. They do establish that the addressable population is substantial and growing. For many, the more useful distinction is between demographic demand and profitable execution. A larger older population creates potential customers. Companies must still deliver desirable locations, appropriate pricing, appealing amenities and disciplined capital allocation. That distinction separates a durable investment thesis from a brochure featuring exceptionally cheerful people holding pickleball paddles.
PulteGroup Offers a Public-Market Connection
Many seeking a listed-company connection to active-adult housing can examine PulteGroup (NYSE: PHM), whose Del Webb brand develops communities for buyers age 55 and older. This is a separate business from The Villages, not an equity stake in its expansion. PulteGroup’s investor overview identifies active-adult buyers as 22% of its buyer mix, alongside 38% first-time buyers and 40% move-up buyers. That provides exposure to retirement-oriented demand within a broader homebuilding platform rather than a single demographic bet. The company has also been extending the concept. In July 2025, PulteGroup announced its entry into the Columbus market with Del Webb Maygrass, an age-restricted community, and Del Webb Explore at Northstar, offering a similar lifestyle concept without the 55-plus requirement. Earlier that year, PulteGroup introduced Del Webb Explore as a resort-style brand open to buyers of any generation. The company said its research found that 40% of potential Del Webb buyers wanted the lifestyle without the age restriction. That is company-sponsored research, not an independent estimate of nationwide demand, but it helps explain the strategy. The investment insight is broader than senior housing: amenities and social connection may appeal across generations. Retirement-oriented development can therefore serve as a testing ground for housing products with a wider audience. For PHM, that is an opportunity worth evaluating. It is not, by itself, evidence that the stock is attractively valued at any particular price.
A 5% Treasury Yield Changes the Retirement Conversation
Housing addresses where retirees might live. Bond yields help determine what they can afford. Yahoo Finance’s October 19 report says the 10-year U.S. Treasury yield closed at 5.09% on the preceding Friday. That is a dated benchmark yield, not a promise that every investor can obtain the same execution price or coupon. Even so, the arithmetic illustrates why the number attracts attention. At an illustrative annual return of 5%:
- $100,000 corresponds to $5,000 a year before taxes.
- $500,000 corresponds to $25,000 a year before taxes.
- $1 million corresponds to $50,000 a year before taxes.
These are simple illustrations, not quoted securities or guaranteed spending plans. A bond’s yield to maturity is not necessarily its cash coupon rate, and the purchase price affects the relationship between cash payments and total return. Treasury notes pay interest every six months and repay principal at maturity. The positive implication is that savers have another meaningful source of nominal income to consider. The limitation is equally important: an attractive percentage does not eliminate the need for a substantial principal balance. Five percent can improve a retirement plan. It cannot retroactively fund one.
“Locking In” Income Does Not Lock Out Risk
The appealing phrase “lock in” deserves a little adult supervision. A fixed-rate bond can provide known contractual payments, but its market value changes as interest rates move. If rates rise, an existing lower-rate bond generally loses market value. An investor who sells before maturity can therefore receive less than expected. Longer maturities generally carry greater interest-rate sensitivity. Inflation is another complication. A fixed nominal payment can buy less over time, even when every payment arrives on schedule. Investor.gov explicitly identifies inflation risk as a concern for fixed-income investors. That makes the bullish case for bonds more measured, and more credible. Higher starting yields can improve the available income proposition. They do not make maturity selection, liquidity needs or purchasing power irrelevant. For retirees, the objective is not to win an argument about where interest rates go next. It is to avoid discovering that next year’s spending money has become an involuntary long-term investment.
Scott Kirby’s Inheritance-Tax Proposal Meets the Kitchen-Table Economy
Against this backdrop, United Airlines (UAL) chief Scott Kirby has introduced a distinctly different wealth-management conversation.
In remarks reported by Yahoo Finance and other outlets, Kirby supported a national wealth tax and said inheritance taxes should “get close to 100% at some level,” adding, “I would pay them.” Reporting on the interview notes that he did not specify the wealth threshold or provide a detailed rate structure. That qualification matters. His comments should not be presented as a proposal to confiscate every family’s inheritance. But the contrast between his financial position and that of an ordinary household is still striking. United’s 2026 proxy statement reports Kirby’s beneficial ownership at 1,255,838 shares under the filing’s reporting rules, a figure that includes options and other holdings detailed in its footnotes. This is evidence of substantial executive equity exposure, not a clean measure of liquid wealth or personal net worth. It is reasonable to describe his career as having created the potential for generational wealth. It would go beyond the available evidence, however, to declare that every member of his family will never need to worry about money. Public disclosures do not establish his complete assets, liabilities, spending commitments or estate arrangements. The fair commentary is sharper than the unsupported claim: a highly compensated executive with substantial equity exposure can debate inheritance taxation from a position of financial security that many middle-class Americans are still trying to reach. There is a considerable difference between deciding how much wealth should survive you and wondering whether your savings will.
The Middle Class Is Playing a Different Financial Game
The Federal Reserve’s 2022 Survey of Consumer Finances provides useful perspective. Median family net worth was $192,900, while mean family net worth was $1,063,700, both measured in 2022 dollars. The much higher mean illustrates how large fortunes pull the average upward. Neither figure should be mistaken for the typical family’s liquid investment portfolio. For many middle-class households, an inheritance is less a dynastic luxury than a possible source of financial resilience: a home, a retirement-account balance or assistance for the next generation. That is why the threshold in Kirby’s suggested tax is not a technical afterthought. It is the central policy question. Current federal law already distinguishes ordinary estates from very large ones. The IRS lists a $15 million basic estate-and-gift-tax exclusion per individual for 2026. Its estate-tax guidance also explains that filing requirements take account of the estate and adjusted taxable gifts. Kirby’s remarks express a policy preference, not enacted law or a fully specified legislative plan. The current exclusion places many middle-class estates far below the federal threshold. Any assessment of a different system would require knowing its exemptions, treatment of spouses and other design details. The constructive economic goal should be broader financial security, not merely a more theatrical argument about the fortunes of people who already have it.
United’s Investment Case Is Separate From Its CEO’s Tax Philosophy
Investors should also distinguish Kirby’s political views from United Airlines’ operating performance. In its 2026 proxy statement, United reported 2025 operating revenue of $59.1 billion, net income of $3.4 billion and operating cash flow of $8.4 billion. The company also reported $2.7 billion of free cash flow, a non-GAAP measure, and diluted earnings per share of $10.20. Those figures provide a substantive basis for evaluating NASDAQ: UAL. They do not establish that the shares are inexpensive today. United also reported a record 27.4 million premium seats flown in 2025, representing 12% of all seats flown. Its premium offering is relevant to a broader discussion of customers willing to pay for comfort, although the filing does not establish how much of that demand comes from retirees. The bullish airline thesis rests on execution, customer demand, cash generation and capital discipline. Fuel costs and other industry stresses remain material considerations, as United itself discusses in the proxy. A chief executive’s tax philosophy may generate headlines. It does not pay for jet fuel.
Where the Retirement Opportunity Becomes Investable
The most compelling reading of these developments is not that every retirement-related asset deserves a higher price. It is that investors have several distinct opportunities to investigate, each with a different return engine.
- Active-adult housing: PulteGroup (NYSE: PHM) offers listed-company exposure through Del Webb, with the broader homebuilding business providing diversification beyond retirement buyers.
- Fixed-income planning: The reported 5.09% 10-year Treasury yield creates a stronger nominal-income starting point, while leaving interest-rate and inflation risks intact.
- Travel and premium service: United Airlines Holdings (NASDAQ: UAL) offers exposure to travel demand and premium-product execution, but should not be treated as a pure retirement-economy investment.
- Development credit: The Villages’ proposed offering illustrates capital demand in retirement housing, but its unrated, high-yield character requires a separate credit analysis rather than a demographic leap of faith.
The opportunity is to connect a growing customer population with businesses that can serve it profitably, while recognizing that households arrive at retirement with profoundly different resources. The Villages is planning more homes. Treasury yields are giving savers something meaningful to calculate. Kirby is asking how much accumulated wealth should pass to the next generation. For many, the productive question is where durable demand meets disciplined execution, without paying a price that assumes retirement comes with a money-back guarantee.
The Sources
- Yahoo Finance / Bloomberg: “World’s Largest Retirement Community Set to Borrow $180 Million”
https://finance.yahoo.com/real-estate/articles/world-largest-retirement-community-set-142613288.html - Yahoo Finance: “United Airlines CEO Says US Should Have an Inheritance Tax Close to 100%, and He’d Pay It”
https://finance.yahoo.com/economy/article/united-airlines-ceo-says-us-should-have-an-inheritance-tax-close-to-100-and-hed-pay-it-214906350.html - Yahoo Personal Finance: “The 10-Year Treasury Yield Is Above 5%. Should Savers Lock In Now?”
https://finance.yahoo.com/personal-finance/investing/article/the-10-year-treasury-yield-is-above-5-should-savers-lock-in-now-193110179.html - U.S. Securities and Exchange Commission: United Airlines Holdings, Inc., 2026 Proxy Statement
https://www.sec.gov/Archives/edgar/data/100517/000110465926040467/tmb-20260519xdef14a.htm - U.S. Census Bureau: “Older Adults Outnumber Children in 11 States and Nearly Half of U.S. Counties”
https://www.census.gov/newsroom/press-releases/2025/older-adults-outnumber-children.html - Federal Reserve: “Changes in U.S. Family Finances From 2019 to 2022”
https://www.federalreserve.gov/publications/october-2023-changes-in-us-family-finances-from-2019-to-2022.htm - PulteGroup: “PulteGroup Introduces Del Webb and Del Webb Explore to the Columbus Market”
https://pultegroupinc.com/investor-relations/news/news-details/2025/PulteGroup-Introduces-Del-Webb-and-Del-Webb-Explore-to-the-Columbus-Market/default.aspx - PulteGroup: “PulteGroup Introduces Del Webb Explore: The Next Generation of Resort Living”
https://pultegroupinc.com/investor-relations/news/news-details/2025/PulteGroup-Introduces-Del-Webb-Explore–The-Next-Generation-of-Resort-Living/default.aspx - PulteGroup: Investor Overview
https://pultegroupinc.com/investor-relations/investor-overview/default.aspx - Investopedia: “Understanding Treasury Notes: Terms, Investment Options, and Benefits”
https://www.investopedia.com/terms/t/treasurynote.asp - Investor.gov / U.S. Securities and Exchange Commission: “Bonds: FAQs”
https://www.investor.gov/introduction-investing/investing-basics/investment-products/bonds-or-fixed-income-products/bonds - U.S. Securities and Exchange Commission: “Investor Bulletin: Interest Rate Risk: When Interest Rates Go Up, Prices of Fixed-Rate Bonds Fall”
https://www.sec.gov/files/ib_interestraterisk.pdf - Internal Revenue Service: “What’s New: Estate and Gift Tax”
https://www.irs.gov/businesses/small-businesses-self-employed/whats-new-estate-and-gift-tax - Internal Revenue Service: “Frequently Asked Questions on Estate Taxes”
https://www.irs.gov/businesses/small-businesses-self-employed/frequently-asked-questions-on-estate-taxes - Fox Business: “United Airlines CEO Calls for National Wealth Tax, Inheritance Taxes Approaching 100%”
https://www.foxbusiness.com/fox-news-travel/united-airlines-ceo-scott-kirby-wealth-inheritance-tax
Stay Updated with Vista Partners
Subscribe to receive market insights, investing ideas, and the latest updates directly in your inbox.
Stocks Slide as Rising Yields and Walmart Shock Risk Assets – Thurs., Aug. 20 -( $DOCS $HPP $MODD $VIX $YSG Rise! )-