A Retinal Bet With Big-Pharma Muscle and Blackstone Financing
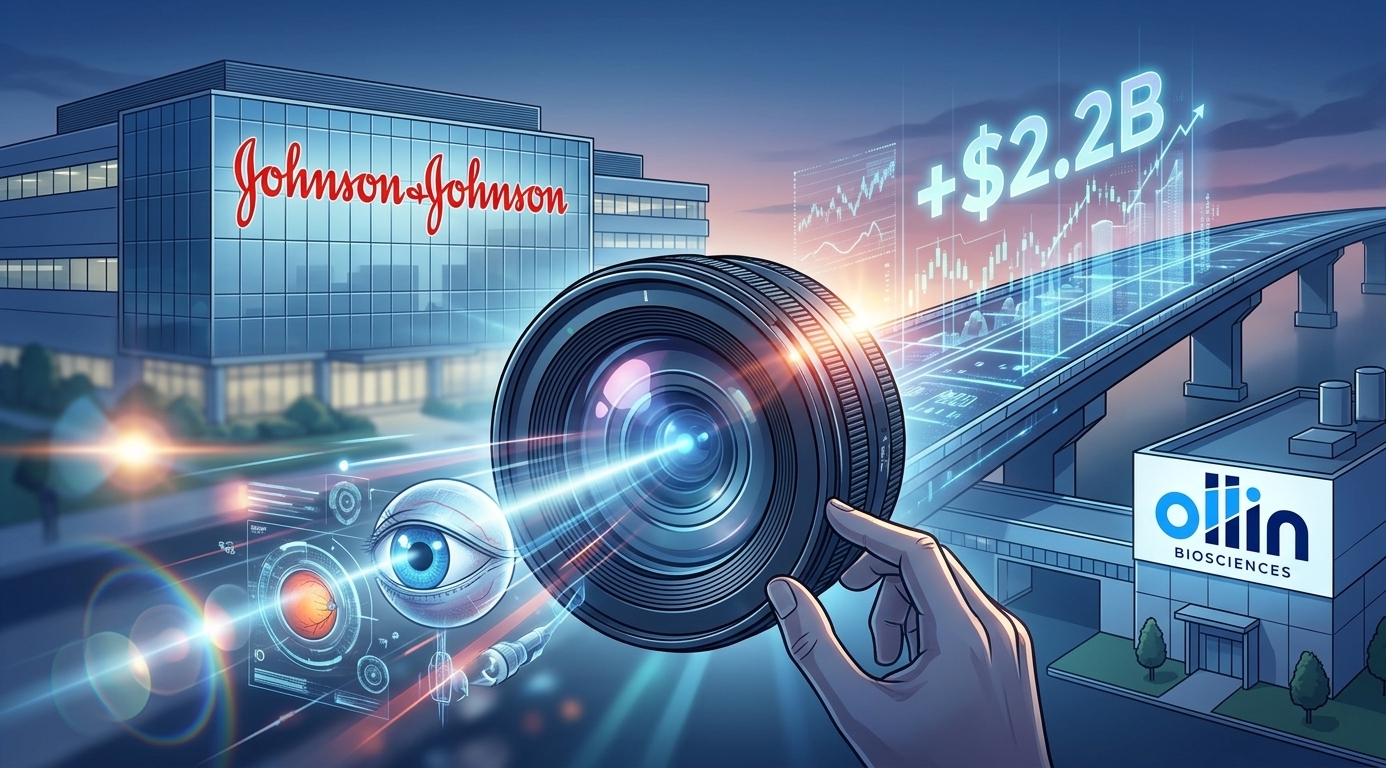
Johnson & Johnson (NYSE: JNJ) is putting substantial capital behind a straightforward proposition: better control of retinal disease, potentially with more time between treatments, would be worth bringing into its pharmaceutical portfolio. On November 16, the healthcare company announced an agreement to acquire Ollin Biosciences for $2.2 billion upfront, securing an investigational eye-disease therapy with late-stage ambitions. Additional regulatory and commercial milestones could bring the acquisition consideration to approximately $3.325 billion. The centerpiece is OLN324, a bispecific antibody being developed for wet age-related macular degeneration, or wet AMD, and diabetic macular edema, or DME. Alongside the acquisition, Blackstone Life Sciences, part of Blackstone (NYSE: BX), has agreed to provide $750 million over multiple years to fully fund the drug’s Phase 3 development, contingent on the acquisition closing. That combination gives the announcement its bullish appeal. Johnson & Johnson would gain a differentiated retinal drug candidate, while specialized outside capital would finance its pivotal development program. The laboratory still has to deliver, but the financing department has already found its reading glasses.
What Johnson & Johnson Is Buying With Ollin Biosciences
OLN324 is designed to target two pathways involved in retinal vascular disease: vascular endothelial growth factor, known as VEGF, and angiopoietin-2, or Ang2. Johnson & Johnson describes the candidate as a small-format antibody, or minibody, with high Ang2 potency that could improve control of retinal fluid. The clinical objective is more effective and sustained disease control. In retinal medicine, an improvement in durability could matter alongside efficacy because Johnson & Johnson is explicitly pursuing the possibility of longer intervals between treatments. Those benefits remain development goals, not established advantages. The potential patient population is substantial. According to Johnson & Johnson, wet AMD and DME together affect more than 40 million people worldwide and are leading causes of vision loss. That figure describes disease prevalence, not the number of patients who would necessarily qualify for, receive or obtain coverage for OLN324. Even with that distinction, the medical need gives the program a meaningful commercial foundation. For many following JNJ, the attraction is therefore not simply that the company has bought another molecule. It is that the molecule addresses a large disease burden with an identifiable proposition: stronger fluid control and potentially more durable treatment effects.
A Development Program With an Existing Scientific Trail
Ollin’s work predates the acquisition announcement. Its website records a March 2026 announcement of final results from a randomized head-to-head study comparing OLN324 with faricimab in wet AMD and DME, followed by additional clinical presentations during the year. Ollin also announced a $330 million Series B financing in June to advance global Phase 3 development. Those milestones show that Johnson & Johnson is acquiring a program with an existing development history, rather than a mechanism accompanied chiefly by an attractive presentation. They do not, by themselves, establish superiority. Johnson & Johnson’s description of “best-in-class potential” is an aspiration that must survive larger clinical trials, regulatory review and eventual commercial competition. The bullish interpretation is that the company sees enough promise to commit significant capital before those questions are settled. There is an important timing distinction as well. Johnson & Johnson describes OLN324 as a Phase 3 investigational asset, while Ollin’s website lists Phase 3 initiation in the second half of 2026. The sound interpretation is that the transaction is centered on late-stage development, not on a completed pivotal evidence package.
Why the Blackstone Agreement Matters
The separate Blackstone arrangement is more than a financing footnote. Blackstone-managed funds would provide Johnson & Johnson with $750 million over multiple years for OLN324’s Phase 3 clinical program. In exchange, Blackstone would become eligible for specified regulatory and sales milestone payments, along with single-digit royalties. The funding depends on Johnson & Johnson completing the Ollin acquisition.The structure pairs pharmaceutical development capabilities with dedicated life-sciences capital. Johnson & Johnson would obtain the asset and direct its advancement, while Blackstone would receive an economic interest tied to future outcomes. It is not free money, and it should not be treated as a simple $750 million discount to the acquisition price. The financing carries future economic obligations. Its appeal is that it supplies designated capital for the next major development stage while distributing the program’s financial exposure. For many assessing the transaction, that is a more useful distinction than the headline purchase price alone. Johnson & Johnson is not merely buying an opportunity. It is arranging how to finance the work required to test it.
Johnson & Johnson Already Has a Substantial Vision Foundation
Ollin would enter a company with an established presence in eye care, not a newcomer looking for directions to the ophthalmology department. Johnson & Johnson’s 2025 Form 10-K describes a Vision portfolio that includes ACUVUE contact lenses, TECNIS premium intraocular lenses and products used in cataract and refractive procedures. The franchise generated approximately $5.47 billion in 2025 sales, an increase of 6.3% from 2024. Growth continued into 2026. First-quarter Vision sales reached approximately $1.365 billion, up 6.7% on a reported basis and 3.6% operationally. Its second-quarter SEC-filed financial schedules reported Vision sales of $565 million in the United States and $887 million internationally, totaling approximately $1.452 billion. The longer comparison is constructive, too. Vision sales were approximately $5.15 billion in 2024, compared with $5.07 billion in 2023. The stronger growth recorded in 2025 provides context for Johnson & Johnson’s willingness to pursue another avenue of eye-care innovation. These existing products and OLN324 should not be confused. Contact lenses, surgical technologies and retinal pharmaceuticals have different development requirements and commercial demands. Still, the proposed acquisition would broaden an established corporate commitment to vision into an additional therapeutic opportunity.
A Large Company Pursuing a Focused Growth Opportunity
The wider Johnson & Johnson business provides useful scale for evaluating the deal. In its October 13 third-quarter release filed with the SEC, the company reported quarterly sales of approximately $25.4 billion, up 5.9%. It also raised its full-year reported sales outlook to a midpoint of approximately $101.2 billion and its adjusted earnings-per-share outlook to a midpoint of $11.10. Those figures predate the Ollin announcement and should not be interpreted as guidance incorporating the acquisition. The implication is favorable but measured. Ollin would not need to carry Johnson & Johnson’s entire growth story. It would add a potentially valuable development opportunity to a business with substantial existing revenue. That makes the acquisition interesting as portfolio construction. Johnson & Johnson can pursue an ambitious retinal program without presenting one experimental medicine as the solution to every corporate question. The company has not yet specified the transaction’s accounting treatment, saying it will communicate that information on or before closing. Accordingly, the announced terms do not support a precise claim about near-term earnings accretion or dilution,
The Milestones That Could Strengthen the JNJ Bullish Case
The proposed acquisition is expected to close before the end of 2026, subject to regulatory approvals and customary conditions. After that, the most meaningful developments would concern the execution and results of OLN324’s late-stage program. For many watching the story, the central questions are practical:
- Can OLN324 demonstrate clinically meaningful disease control in larger trials?
- Can it support longer treatment intervals without sacrificing outcomes?
- Will its safety profile remain suitable for the intended patient population?
- Can any clinical differentiation translate into physician adoption and reimbursement?
Those questions follow directly from the product profile Johnson & Johnson is pursuing and the development and commercialization risks it identifies. The bullish case does not require pretending that they have already been answered. It rests on the combination of a substantial medical need, a differentiated investigational approach, a committed pharmaceutical buyer and an identified source of pivotal-development funding.
Eupraxia Adds a Different Durability Story Ahead of December Data
Toward the smaller-company end of biotechnology, Eupraxia Pharmaceuticals (NASDAQ: EPRX; TSX: EPRX) offers another example of why treatment duration can become a compelling development theme, although its program concerns a different disease and a different technology. A November 11 Vista Partners article highlighted Eupraxia’s approaching December 2026 interim analysis from the randomized, placebo-controlled Phase 2b portion of RESOLVE. The trial is evaluating EP-104GI for eosinophilic esophagitis, or EoE, an inflammatory condition that can make swallowing painful and difficult. Eupraxia’s November 10 SEC-filed update confirms that the study reached its targeted enrollment of 120 patients. The Phase 2b program is evaluating 120 mg and 160 mg doses, each delivered through 20 esophageal-wall injection sites, with interim results expected in December. Its Diffusphere platform is designed to provide localized, extended-release drug delivery. The early durability findings explain the interest. Eupraxia reported that 64% of patients remained in clinical remission over a 52-week period in its open-label experience. In the highest-dose cohort, two of three patients maintained clinical remission at 52 weeks. The denominator matters: three patients can generate a promising signal, but not a dependable forecast for a broader population. The balance sheet adds substance to the catalyst. At September 30, Eupraxia held $75.2 million in cash and cash equivalents and $51.2 million in short-term investments, totaling $126.4 million. Management expected existing resources to fund operations into the second half of 2028. The company also reported a third-quarter net loss of $15.2 million, compared with $6.4 million a year earlier, primarily reflecting increased development and administrative spending. As the Vista Partners article notes, EoE already has established treatments, including Dupixent from Sanofi (NASDAQ: SNY; Euronext Paris: SAN) and Regeneron Pharmaceuticals (NASDAQ: REGN), and Eohilia from Takeda Pharmaceutical (NYSE: TAK; Tokyo: 4502). Eupraxia’s opportunity is to establish a persuasive clinical and practical role for sustained local delivery, not simply to arrive in an empty market. Nothing in the cited materials establishes an acquisition connection between Eupraxia and the Ollin transaction. The useful connection is narrower: both development stories place value on the possibility of longer-lasting treatment effects. Eupraxia’s December controlled data will provide a more rigorous test of its own proposition than the earlier open-label observations.
The Larger Opportunity: Making Treatment Last
Johnson & Johnson’s Ollin agreement is compelling because its components fit together: a retinal drug candidate aimed at a substantial medical need, an established healthcare company prepared to advance it and a specialist financing partner prepared to fund pivotal development. For JNJ, the opportunity is to expand an already meaningful vision business with a potentially differentiated pharmaceutical asset. For EPRX, the nearer-term opportunity is to show whether an encouraging durability signal can withstand a controlled clinical test. The companies differ dramatically in scale, but the question is recognizably similar: can a better treatment experience become a better healthcare business? The market can reward an elegant hypothesis. The more durable reward usually requires data that remain persuasive after the presentation ends.
The Sources
- Johnson & Johnson: Agreement to Acquire Ollin Biosciences and OLN324, November 16, 2026
- Blackstone: $750 Million R&D Funding Agreement for OLN324, November 16, 2026
- Ollin Biosciences: Pipeline, Clinical Development History and Company Announcements
- SEC.gov: Johnson & Johnson 2025 Annual Report on Form 10-K
- SEC.gov: Johnson & Johnson First-Quarter 2026 Form 10-Q
- SEC.gov: Johnson & Johnson Second-Quarter 2026 Financial Schedules, Exhibit 99.2
- SEC.gov: Johnson & Johnson 2024 Annual Report on Form 10-K
- SEC.gov: Johnson & Johnson Third-Quarter 2026 Results and Updated Guidance, Exhibit 99.1
- SEC.gov: Eupraxia Pharmaceuticals Third-Quarter 2026 Results and RESOLVE Update, Exhibit 99.3
- Vista Partners: Eupraxia Pharmaceuticals’ Story Gains Weight & Attention Ahead of December EoE Data, November 11, 2026
Stay Updated with Vista Partners
Subscribe to receive market insights, investing ideas, and the latest updates directly in your inbox.